Living Benefits & IUL
Living benefits and indexed universal life, explained in plain English
Coverage that may help while you are living, and flexible permanent coverage with cash value tied to a market index.
Free Consultation
Life insurance that can do more than pay a death benefit
Living benefits are policy riders that may let you use part of your death benefit early if you are diagnosed with a qualifying terminal, chronic or critical illness. Indexed universal life (IUL) is a type of permanent life insurance whose cash value can earn interest based partly on a stock market index.
Both can be useful, and both have rules and trade-offs worth understanding. Jay will explain how a specific policy works, including costs, limits and what happens in different scenarios, before you decide.
- Riders that may advance part of the benefit for serious illness
- Flexible premiums and adjustable death benefit on IUL
- Cash value interest linked to an index, with caps and floors
- A clear walkthrough of costs and risks before you apply
Prefer to talk? Call or text (949) 822-8702.
Jay Romero, CA Insurance License #0C93169 · DRE 01343079
Licensed CA Life Agent
CA Insurance License #0C93169
Over 25 Years
in Southern California real estate
Bilingual
English & Español
Free Consultation
No cost and no obligation
Living benefits
What living benefits riders do
An accelerated death benefit rider may let you receive part of your policy’s death benefit while you are alive if you meet the policy’s definition of a terminal, chronic or critical illness. Families use that money for treatment, care, lost income or keeping up with the mortgage.
Any amount paid early reduces the death benefit your beneficiaries receive later, and some riders charge a fee or apply a discount when used. Which riders are available, and how they are defined, varies by carrier, policy and state.
Indexed universal life
How indexed universal life (IUL) works
IUL is permanent life insurance with flexible premiums. After the policy’s charges are deducted, the cash value can be credited with interest based on the performance of an index, such as the S&P 500, up to a cap or participation rate set by the carrier. Most policies also have a floor, often 0%, so a down year in the index does not cause an index loss, though policy charges still apply.
Your money is not invested directly in the stock market, and an IUL is not an investment account. Caps, participation rates and charges can change, illustrations are not guarantees, and if the cash value does not keep up with the policy costs, you may need to pay more to keep coverage in force. Policy loans and withdrawals reduce the cash value and death benefit and can cause a lapse.
Is it right for you?
Who considers living benefits and IUL
Living benefits riders are worth asking about for almost anyone buying coverage, especially families whose budget depends on one income. IUL tends to fit people who want permanent coverage, can fund the policy consistently over many years, and want flexibility in premiums and death benefit.
If your main goal is the most protection for the lowest cost, term life may be the better fit, and you can ask about living benefits riders on term policies too. Jay will help you compare options side by side. For retirement or tax planning, also talk with your financial and tax professionals.
Is It Right for You?
Who this coverage is a good fit for
- Families who want protection if a serious illness hits
- People who want permanent, flexible coverage
- Business owners and higher earners planning long term
- Anyone comparing IUL with whole life or term
Not sure how much coverage you need? Start with the free calculator, then talk it through with Jay.
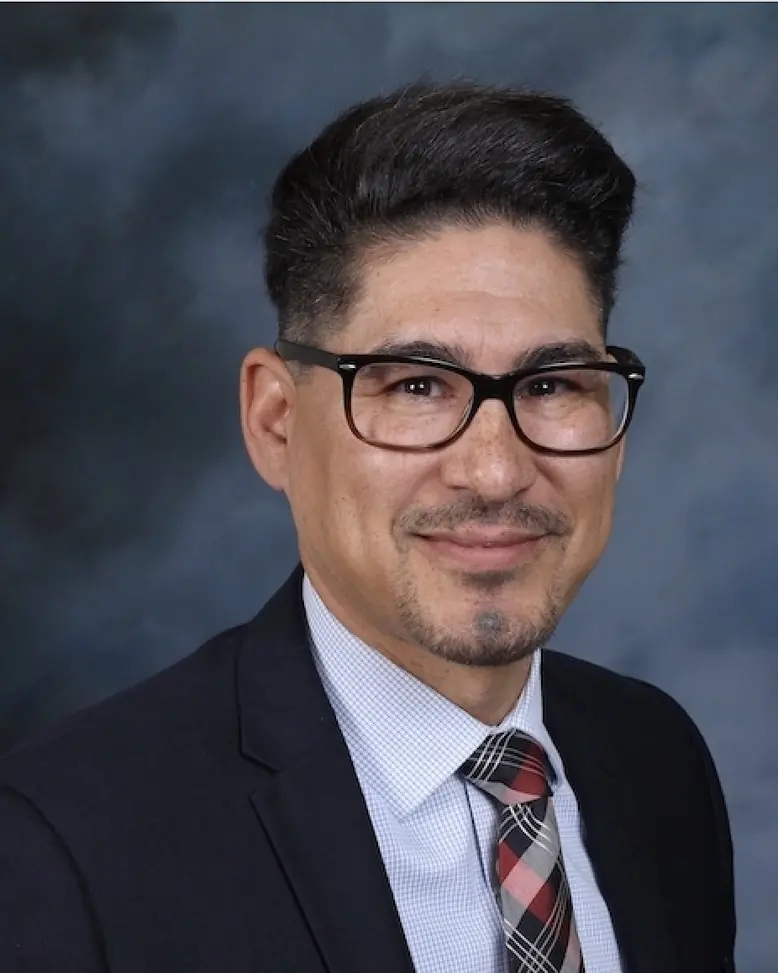
Work With Jay
The same person you trust with your home
Jay Romero has over 25 years of Southern California real estate experience helping buyers, sellers and investors. He is also a licensed California life insurance agent (CA Insurance License #0C93169), so you can plan for your home and your family’s protection with one person you already know.
- Licensed California life insurance agent
- Over 25 years of real estate experience
- Clear answers with no pressure
- Bilingual service in English and Spanish
How It Works
Get covered in three simple steps
01
Consult
A quick call about your family, your home and your goals. No cost and no obligation.
02
Compare options
Jay explains the policy types and coverage amounts that fit your budget, in plain language.
03
Apply & protect
Jay helps with the application. Coverage begins once the carrier approves it and the policy is issued.
Questions
Frequently asked questions
What are living benefits on life insurance?
Living benefits are riders that may let you access part of your death benefit early if you are diagnosed with a qualifying terminal, chronic or critical illness. Using them reduces the amount your beneficiaries receive.
Is indexed universal life a good investment?
IUL is life insurance, not an investment. Its cash value can be credited with interest based on an index, subject to caps, floors and policy charges. It works best for people who need permanent coverage and can fund it consistently.
Can I lose money in an IUL?
The floor usually protects against index losses, but policy charges are still deducted. If the cash value does not cover the costs, you may need to pay more premium or the policy could lapse.
Are living benefits included with every policy?
No. Availability, definitions and costs of riders vary by carrier, policy and state. Jay will tell you exactly what a policy includes before you apply.
Explore more coverage options
Life insurance overview · Term Life Insurance · Whole Life Insurance · Mortgage Protection Life Insurance · Final Expense Insurance · Life Insurance for Business Owners & Investors · Life insurance calculator
Get Started
Ready to protect your family? Talk with Jay
Jay Romero, CA Insurance License #0C93169 · DRE 01343079
Miamar Realty · Call or text (949) 822-8702
Coverage is subject to underwriting and carrier approval. Policies are offered through Jay Romero’s licensed carrier appointments, including Farmers New World Life Insurance Company. Product features, riders and availability vary by carrier and state. This page is general information, not a quote, a contract of insurance, or tax, legal or investment advice.